Sub: Special cash package equivalent in lieu of Leave Travel
Concession fare for central government employees during the Block
2018-2021.
In this context, it is intimated that the following points may please
be adhered to while submitting the LTC special cash package claims:
1. If an individual is opting for both LTC cash package and leave
encashment then a single claim may be prepared: and submitted to this
section for audit and payment.
2. The claim may be submitted within the stipulated time frame. As
per instant order, claims Shall be settled on or before 31st March 2021.
3. Specimen signatures of countersigning authorities may be sent to this office at the earliest.
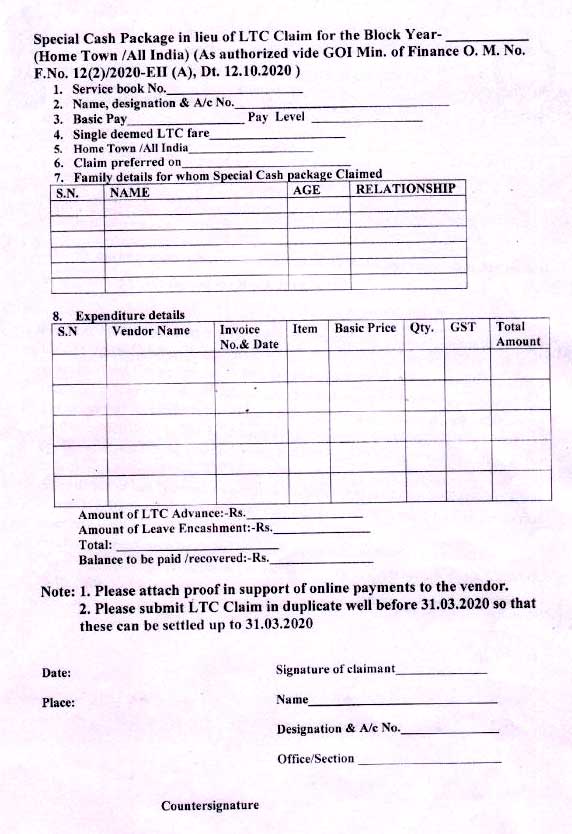
4. A certificate of family members details for which the special cash
package equivalent in lieu of LTC fare has been claimed may be enclosed
with the claim(As per format attached).
5. Proof of payment made by digital mode may please be enclosed along with the claim.
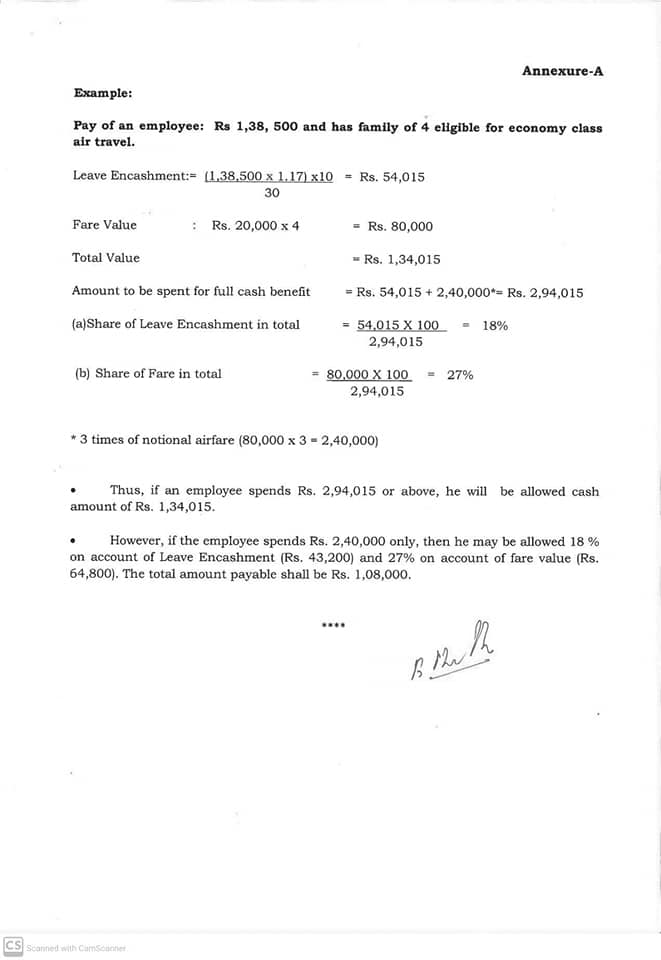
6. Claim may please be prepared as per the example given in Annexure A of MOF OM dt 12.10.2020.
Special cash package equivalent in lieu of Leave Travel Concession Fare for Central Government Employees during the Block 2018-21
F.No.12(2) /2020-EII(A) Ministry of Finance Department of Expenditure EN(A) Branch
North Block, New Delhi 12th October, 2020
Office Memorandum
Sub: Special cash package equivalent in lieu of Leave Travel Concession Fare for Central Government Employees during the Block 2018-21.
In view of Covid-19 pandemic and resultant nationwide lockdown as well as disruption of transport and hospitality sector, as also the need for observing social distancing, a number of Central Government employees are not in a position to avail themselves of LTC for travel to any place in India or their Hometowns in the current Block of 2018-21.
2. With a view to compensate and incentive consumption by Central Government employees thereby giving a boost to consumption expenditure, it has been decided that cash equivalent of LTC, comprising Leave Encashment and LTC fare of the entitled LTC may be paid by way of reimbursement, if an employee opts for this in lieu of one LTC in the Block of 2018-21 subject to the following conditions:-
a) The employee spends the money of a larger sum than the entitlement on account of LTC on actual expenditure.
b) Cash equivalent of full leave encashment will be allowed, provided the employee spends an equal sum. This will be counted towards the number of leave encashment on LTC available to an employee.
C) The deemed LTC fare for this purpose is given below :-
Category of employees
Deemed LTC fare per person (Round Trip)
Employees who are entitled to business class of airfare
Rs. 36,000
Employees who are entitled to economy class of airfare
Rs. 20,000
Employees who are entitled to Rail fare of any class
Rs. 6,000
Deemed LTC fare per person Central Government Employees
d) The cash equivalent may be allowed if the employee spends a sum 3 times of the value of the fare given above.
e) The amount both on account of leave encashment and fare shall be admissible if the employee spends (i) an amount equal to the value of leave encashment and; (ii) an amount 3 times of the cash equivalent of deemed fare, as given above on purchase of such items / availing of such services which carry a GST rate of not less than 12% from GST registered vendors / service providers through digital mode and obtains a voucher indicating the GST number and the amount of GST paid.
f) The admissible payment shall be restricted to the full value of the package [leave encashment as admissible for LTC and deemed fare] or depending upon the spending as per example given at Annexure-A.
g) While TDS is applicable in the case of leave encashment, since the cash reimbursement of LTC fare is in lieu of deemed actual travel, the same shall be allowed exemption on the lines of existing income-tax exemption available to LTC fare. The legislative amendment to the provisions of the Income-Tax Act, 1961 for this purpose shall be proposed in the due course. Hence, TDS shall not be required to be deducted on the reimbursement of deemed LTC fare.
3. Head of the Departments / DDOs may make reimbursement under this package as per the details given above on receipt of invoices of purchases made / services availed during the period post the issuance of this order from the employees who are desirous to avail this package. It may be noted that in order to avail this package an employee should opt for both leave encashment and LTC fare.
4. An amount upto 100% of leave encashment and 50% of the value of deemed fare may be paid as advance into the bank account of the employee which shall be settled based on production of receipts towards purchase and availing of goods and services as given in Para 2(e). The claims under this package (with or without advance) are to be made and settled within the current financial year. Non-utilization / under-utilization of advance is to be accounted for by the DDOs in accordance with the extant provisions relating to LTC advance i.e. immediate recovery of full advance in the case of non-utilisation and recovery of unutilized portion of the advance with penal interest.
5. These orders will take effect from the date of issuance of this Office Memorandum and will be in force during the current financial year till 31st March, 2021.
6. All the Ministries/ Departments are requested to bring the contents of this OM to the notice of all its Attached and Subordinate offices for their information.
Civilian Central Government servants posted in North-Eastern Region, Union Territory of Ladakh, Andaman &
Nicobar Islands and Lakshadweep groups of Islands, who leave their family behind at the old headquarters or
another selected place of residence shall be allowed “Emergency Passage Concession” on two additional
occasions during their entire service career to enable the Government employees and/or their families
[restricted only to spouse and dependent children] to travel either to the Home Town or the station of
posting an emergency
7th CPC LTC
facilities to Central Government Employees serving in North-Eastern Region, Ladakh region of State of Jammu
& Kashmir and in Union Territories of Andaman & Nicobar Island and Lakshadweep Group of
Islands
No. 31011/12/2015-Estt.(A-IV)
Government of India
Ministry of Personnel, Public Grievances and Pensions
Department of Personnel and Training
Establishment A-IV Desk
North Block, New Delhi-110001
Dated: February 28, 2020
OFFICE MEMORANDUM
Subject: LTC facilities to the Civilian employees of the Central Government serving in States of the
North-Eastern Region, Ladakh region of State of Jammu & Kashmir and in Union Territories of Andaman &
Nicobar Island and Lakshadweep Group of Islands - Implementation of recommendations of 7th CPC -
clarification reg.
The undersigned is directed to refer to this Department’s O.M. of even no. dated 24.04.2018 on the subject
noted above and to say that as per para 5 of the aforesaid O.M., civilian Central Government servants posted
in North-Eastern Region, Union Territory of Ladakh, Andaman & Nicobar Islands and Lakshadweep groups of
Islands, who leave their family behind at the old headquarters or another selected place of residence shall
be allowed “Emergency Passage Concession” on two additional occasions during their entire service
career to enable the Government employees and/or their families [restricted only to spouse and dependent
children] to travel either to the Home Town or the station of posting an emergency.
In this regard, this Department is in receipt of references seeking clarification as to whether the facility
of “Emergency Passage Concession” is available to the Government servant for travel from the station
of posting to Home Town only whether the Government servants can avail the facility to travel to the selected
place of residence of family declared by them for the duration of their posting /transfer to these regions
The matter has been considered in this Department in consultation with Department of Expenditure. It is
clarified that “Emergency Passage Concession” can be availed by Government employees posted in North-
East Region, Andaman & Nicobar Islands, Lakshadweep Islands and Union Territory of Ladakh to visit any
one of the destinations, i.e. Home Town or any selected place of residence of the family declared by them for
the duration of their posting/transfer to these regions.
No. 43020/21 2016-Estt (A.IV)
Government of India
Ministry of Personnel, Public Grievances and pensions
Department of Personnel and Training
Establishment A-IV Desk
North Block, New Delhi-110001
Dated: February 19, 2020
OFFICE MEMORANDUM
Subject:- Clarification regarding relaxation of purchase of air tickets from authorized Travel Agents for the purpose of LTC.
The
undersigned is directed to refer to this Department’s o.M. No.
31011/412014- Estt.A-IV dated 19.06.2014 and subsequent o.M. regarding
the procedure for booking of air-tickets on LTC
and to say that as per the extant instructions, whenever a Government
servant claims LTC by air, he/she is required to book the air tickets
directly from the airlines (Booking counters, website of airlines) or by
utilizing the services of the authorized travel agents viz. M/s Balmer
Lawrie & company, M/s Ashok Travels & Tours and IRCTC, (to the
extent IRCTC is authorized as per DoPT O.M. No. 31011/6/2002-Est(A) dated 02.12.2009) while undertaking LTC journey(s).
2.
In this regard, many cases pertaining to the period of 2010-13 have
been reported in this Department where Government employees had traveled
on LTC by air to visit Jammu & Kashmir (J&K) and North-East
Region (NER) under the special dispensation scheme after booking the
tickets through private travel agents due to lack of awareness of rules
at that time. It has been observed that claims of these Government
servants were initially settled by the administrative authorities.
However, after few years when the audit authorities noticed the lapses,
objections were raised on these claims and recoveries were ordered in
such cases along with charging of penal interest. In view of the
financial hardships caused to these individuals, huge demands are being
received from Ministries/ Departments and JCM for grant of one time
relaxation in these cases.
The matter has been
considered in this Department in consultation with Joint consultative
Machinery - staff side and Department of Expenditure. It has been
decided to grant one time relaxation to such Government employees who
had availed LTC
by air to visit J&K and NER during the period of January. 2010 -
June. 2014 and booked the tickets through travel agents other than ‘M/s
Balmer Lawrie & company’, ‘M/s Ashok travels & Tours’ and
'IRCTC' due to lack of awareness of rules. such relaxation shall be
granted with the concurrence of Financial Advisor of the concerned
Ministry/ Department. Fulfillment of fare limit of LTC-80 and other LTC
conditions prevalent at the time of performance of journey by the
Government servants may be ascertained before granting such relaxations.
The Administrative Ministries/ Departments shall also ensure that only
those cases are considered for relaxation where it is established that
bonafide mistake has occured and no undue benefit has accrued
to/obtained by the Government servant.
Further, in this
regard, it is reiterated that the extant instructions regarding booking
of air tickets on LTC journey through authorized modes should be
strictly complied with. It is seen that despite reiterating the above
provisions from time to time, this Department is still in receipt of
cases seeking relaxation for booking of tickets from private travel
agents on the grounds of lack of awareness of rules and work-exigencies.
Therefore, Ministries/ Departments are again advised to ensure wide
circulation of this Department’s instructions issued vide O.M. No.
310111212018-Estt.A-IV dated 10.12.2018, among their employees.
Henceforth, the cases seeking relaxation on the plea of lack of
awareness of rules and on grounds of exigencies of work shall not be
considered by this Department. Only those cases, where the
Administrative Ministry/ Department will certify the fact that bonafide
mistake has occured and undue hardship is being caused to the Government
servant, shall be considered by this Department.
(Surya Narayan Jha)
Under Secretary to the Government of India
To
The Secretaries
All Ministries/ Departments of Government of India
(As per the standard list)
Grant of one time relaxation to the Central Government Employees who have availed LTC-80 and traveled by air by
purchasing ticket from authorities other than authorized agents
Shiva Gopal Mishra
Secretary
Ph: 23382286
National Council (Staff Side)
Joint Consultative Machinery
For central Government
Employees
13-C, Ferozshah Road, New Delhi - 110 001
E Mail: nc.jcm.np@gmail.com
No.NC-JCM-2019/DOPT (LTC)
September , 2019
The Secretary
Government Of India
Department of Personnel and Training
North Block
New Delhi
Sub: Grant of one time relaxation to the Central Govt. Employees who have availed LTC-80 and traveled by air by
purchasing ticket from authorities other than authorized agents
Dear sir,
The above demand was discussed as Item No.15 of the standing committee meeting of the National Council (JCM) held on 7-3-
2019. The extract from the minutes of the above meeting is gives below for your kind ready reference.
Staff side proposed that
if the employee has actually traveled in Air India flight, then the LTC-80 fare of the journey day may be paid to him
irrespective of the fact that ticket was purchased from authorized agent or not. Any excess amount over and above the LTC-
80 fare can be recovered;
No disciplinary action and stoppage of future LTC may be taken;
A general instruction in this regard may be issued to all the Departments to regularize all the pending LTC-80 cases as
above.
‘Chairman agreed to consider the demand of the staff side’.
Sir, as agreed in the meeting a general instruction as above has not yet been issued by the DOP&T. It is therefore
requested that since the employees are subjected to undue hardship, necessary instructions in this regard may please be
issued at the earliest.
Thanking you
Review of charges realised by Indian Railways for verification of PNR details
GOVERNMENT OF INDIA
MINISTRY OF RAILWAYS
(RAILWAY BOARD)
No.2016/TG-I/ 20/P/LTC
New Delhi, Dated 18.07.2019
The Principal Chief Commercial Managers,
All zonal Railways.
(COMMERCIAL CIRCULAR NO. 34 of 2019)
Sub: Review of charges realised by Indian Railways for verification of PNR details.
Ref: Letter nos. 2006/TG-I/ 20/P/ LTC dated 10.01.2007, 2006/TG-I/ 20/P/LTC dated 31.08.2010 (CC No. 40 of 2010), 2006/TG-I/ 20/P/ LTC Pt. dated 13.12.2011 (CC No. 65 of 2011)
In supersession of above referred instructions regarding levy of charges for verification of PNR details etc., Competent Authority have now decided to adopt the following procedure for furnishing information regarding verification of journey details:
(i) Individuals seeking information for self travel under RTI Act or otherwise: It should be provided as per provisions of RTI Act subject to submission of identity proof bearing name and date of birth i.e. Aadhar/PAN card etc. to confirm that the person seeking information is one and the same as one of the passengers on the PNR.
(ii) Individuals seeking information for travel of other person under RTI Act or otherwise: Action should be taken as per relevant provisions of RTI Act and information should not be provided unless consent of third party is available.In case of requests not received under RTI Act, no information shall be provided.
(iii) Government Departments seeking information for their employees for the purpose of reimbursement of travel expenditure: It should be provided on realisation of nominal fee of Rs.50/- per PNR only on receipt of official request from the concerned Department.
(iv) Government Investigating Agencies/ Courts seeking information in connection with investigation/ Court Case: Status quo may be maintained and information shall be provided free of charge on receipt of official request of the Agency.
2. Authority to provide information and to take charges: Concerned Zonal Railways shall decide on the authority to provide information under this policy and to realise charges.
Sd/-
(Shelly Srivastava}
Director Passenger Marketing
Railway Board
Central Civil Services (Leave Travel Concession) Rules, 1988 -Relaxation to travel by air to visit North East Region, Jammu & Kashmir and Andaman & Nicobar - clarification reg
No. 31011/3/2018-Estt. (A-IV)
Government of India
Ministry of Personnel, public Grievances and Pensions
Department of personnel and Training
Establishment A-IV Desk
North Block, New Delhi-110001
Dated: June 20,2019
OFFICE MEMORANDUM
Subject:- Central Civil Services (Leave Travel Concession) Rules, 1988 -Relaxation to travel by air to visit North East Region, Jammu & Kashmir and Andaman & Nicobar - clarification reg
The undersigned is directed to refer to this Department's O.M. of even no. dated 20.09.2018 regarding the relaxation to travel by air on LTC to visit North-East Region (NER), Jammu & Kashmir (J&K) and Andaman & Nicobar Islands (A&N) and to say that as per para 2(v) of the aforesaid O.M., Government employees non-entitled to travel by air are allowed air travel in Economy class subject to maximum fare limit of LTC-80 fare in the following sectors:
a) Between Kolkata/ Guwahati and any place in NER. b) Between Kolkata/ Chennai/ Visakhapatnam and Port Brair. c) Between Delhi/ Amritsar and any place in J&K.
Journey for these non-entitled.employees from their Headquarters up to Kolkata/ Guwahati/ Chennai/ Visakhapatnam/ Delhi/ Amritsar is to be undertaken as per their entitlement.
2. In this regard, several references / RTI applications are received in this Department seeking clarification regarding settlement of LTC claims where a non-entitled Government employee directly travels by air from his Headquarters to the destination in North-East Region (NER), Jammu & Kashmir (J&K) and Andaman & Nicobar Islands (A&N) as opposed to their entitlement.
3. The matter has been examined in this- Department in consultation with Department of Expenditure. It has been decided that cases of direct air travel by a non-entitled Government on LTC from his Headquarters !o special dispensation the place oi visit in NER/ J&K / A&N under the special dispensation scheme of travel by air as under:
"Entitled class rail fare from the.Headquarters/ place of posting to the nearest relevant railhead (ie. Kolkata/ Guwahati/ Delhi/ Amritsar/ Chennai/ Visakhapatnam) based on the place of visit (in NER / J&K/ A&N) + LTC-80 Economy class air fare from the same railhead to the place of visit in NER / J&K / A&N ); or the actual air fare from the Headquarters to the place of visit, whichever is less."
4. In their application to the staff serving in the Indian Audit and Accounts Department, this order issues after consultation with Comptroller & Auditor General of India.
(Surya Narayan Jha)
Under Secretary to the Govt. of India
To
The Secretaries
All Ministries/ Departments of the Government of India.
(As per the standard list)
Updated list of All India LTC fare under LTC 80 Scheme for May 2019 Features of LTC Concession by Air India
Eligibility: Employees of the State and Central Governments/ Public sector undertaking travelling on leave. Employees of the Educational Institutions recognized by Central/ State Govt or affiliated to any University/ Educational board are also eligible.
Required Documents: Official ID card. Family members to carry the copy of the same.
Discount: Specified fare.
Travel: Any sector within India.
Ticket Validity: 1 Year from date of issue
Advance Purchase: Not required. Ticket can be purchased any time
Children: No discount applies.
Infant: (Under 2 years) 1st accompanying Infant – Rs.1000 per coupon, Plus applicable taxes. 2nd and more Infants, no discount permissible.
In case the relevant ID / documents are not presented at the time of check in or at the boarding gate, the basic fare will be forfeited and the tickets will become non refundable (only taxes & levies will be refunded). Boarding will be denied if the identity proof is not provided at the time of check in and at the boarding gate.
DoE: Guidelines on Air Travel on Official Tours - Purchase of air ticket from authorized
agent
No.N-20011/29/2016-E.II(pt.IV)
Government Of India
Ministry of Road Transport & Highways
(Establishment Section-II)
Transport Bhawan, 1, parliament Street, New Delhi-110001
New Delhi, Dated February, 2019
CIRCULAR
Sub:- Guidelines on Air Travel on Official Tours-purchase of air ticket from authorized agent -
reg.
The undersigned is directed to refer to Department Of Expenditure, ( Ministry of Finance) O.M No.
19024/22/2017.E.IV dated 19.07.2017 and 27.02.2018 (Copy Enclosed) on the subject mentioned above
and to request all officers for strict compliance of extant air travel guidelines, as henceforth,
relaxation on account Of ignorance,’ unawareness about these guidelines would not be considered in
future.
Accordingly, all CES (Roads) officers are hereby requested for strict compliance of the same.
sd/-
(Kamal Kishore)
Under Secretary to the Government of India
Guidelines on Air Travel on Official Tours - Purchase of air ticket from authorized agent
No.19024/22/2017-EIV
Government of India
Ministry of Finance
Department of Expenditure
North Block, New Delhi
Dated the 27th February, 2018
Office Memorandum
Subject: Guidelines on Air Travel on Official Tours - Purchase of air ticket from authorized
agent.
The undersigned is directed to refer to this Departments’ O.M No, 19024/22/2017-E.IV dated
19.07.2017 regarding guidelines on Air travel where the Govt. of India bears the cost of passage. As
per this O.M., Ministries/Departments were asked to ensure that these instructions are given
adequate coverage and were to be circulated to all so that ‘lack of knowledge’ of the rules is not
cited as an excuse. In spite of these instructions, a large number of cases for relaxation of air
travel guidelines due to purchase of air ticket from unauthorized travel agents, are still being
received in this Department.
The matter has been re-considered and it has been decided that all such cases of air travel where
tickets have been purchased after issue of this Department’s O.M. dated 19.07.2017, seeking
relaxation of air travel guidelines pertaining to purchase of air ticket from authorized agent,
should have the approval of Secretary of the Administrative Ministry before referring the same to
Department of Expenditure.
This is issued with the approval of Secretary Expenditure.
sd/-
(Nirmala Dev)
Deputy Secretary to the Government of India
Regulation of LTC claims when portion of journey are
performed by private transport
F.No.20-04/2015-PAP
Government of India
Ministry of Communications
Department of Posts
(Establishment Division)
Dak Bhawan, Sansad Marg,
New Delhi - 110001.
Dated: 15 February, 2019.
To
All Chief Postmasters General/ Postmasters General
Chief
General Manager, BD Directorate/Parcel Directorate/ PLI
Directorate
Director RAKNPA/ GM CEPT/ Directors of All
PTCs,
Addl. Director General, Army Postal Service, R.K.
Puram, New Delhi
All General Managers (Finance)/ DAP/
DDAP
Sub: Regulation of LTC claims when portion of journey
are performed by private transport - Regd.
This Directorate has sought clarification from the Nodal
Ministry regarding reimbursement of LTC claims where a part of
the journey (be it in the beginning, middle or end) has been
performed by the Government servant by unauthorized mode of
transport (private bus/private taxi etc.) and rest of the
journey to the declared place of visit by authorized mode of
transport.
The Nodal Ministry has issued following
clarification:
(I) DOP&T’s OM no. 31011/3/2015-Estt. (A.IV) dated
09.02.2017 provides that cases where a Government servant
travels on LTC upto the nearest airport/railway station/bus
terminal by authorized mode of transport and undertakes rest of
the journey to the declared place of visit by private transport/
own arrangement (such as personal vehicle or private taxi etc.),
may be dealt with as follows:-
(a) In all such cases the Government servant may be required
to submit a declaration that he and the members of the family in
respect of whom the claim is submitted have indeed travelled
upto the declared place of visit.
(b) If a public transport is available in a particular area,
the Government servant will be reimbursed the fare admissible
for journey by otherwise entitled mode of public transport from
the nearest airport/railway station/bus terminal to the declared
place of visit by shortest direct route.
(c) In case, there is no public transport available in a
particular stretch of journey, the Government servant may be
reimbursed as per his entitlement for journey on transfer for a
maximum limit of 100 kms covered by the private/personal
transport based on a self-certification from the Government
servant. Beyond this, the expenditure shall be borne by the
Government servant.
(II) In view of the above provisions, a Government employee
shall get fare reimbursement in cases where the initial or end
part of the LTC journey from the source/destination to the
nearest railhead/airport or vice-versa, as the case may be, has
been performed by a private/personal mode of transport while the
major part of the journey from the nearest railhead/airport has
been performed by the authorized mode of transport.
Taking into account the advice of the Nodal Ministry in this
regard, action may kindly be taken in similar cases only on the
basis of the above advice and in any case of deviation from the
above, the advice of the Directorate may be sought for.
sd/-
(S.B. Vyavahare)
Assistant Director General (Estt.)
Ministry of Personnel, Public Grievances & Pensions LTC in Flights Under Udaan Scheme
07 FEB 2019
At present, the officials of Central Government are allowed to travel
by Air India flights only while availing LTC. However, the facility to
avail tickets in all airlines including private airlines is admissible
at present in case of LTC in lieu of Home Town/All India LTC travel to
North East Region (NER), Jammu & Kashmir (J&K) and Andaman &
Nicobar (A&N), in relaxation to Central Civil Services (Leave
Travel Concession) Rules, 1988 under certain conditions. There is no
proposal at present to allow Government officials to travel by private
airlines for the purpose of LTC.
This information was provided by the Union Minister of State
(Independent Charge) Development of North-Eastern Region (DoNER), MoS
PMO, Personnel, Public Grievances & Pensions, Atomic Energy and
Space, Dr Jitendra Singh in written reply to a question in Rajya Sabha
today.
LTC for New Joining Central Government Employees - FAQ
Frequently Asked Questions on LTC entitlements of Fresh Recruit
Frequently Asked Questions (FAQs) on Leave Travel Concession entitlements of Fresh Recruit
The
6th CPC had recommended that "Fresh Recruits" to the Central Government
may be allowed to travel to their Home Town along with their families
on three occasions in a block of four years and to any place in India on
the fourth occasion. This was accepted by the Government and orders
were issued vide DoPT O.M. No. 31011/4/2008-Estt.(A) dated 23rd
September, 2008.
This Department receives a number of references
seeking clarifications from various Ministry/ Departments about the year
wise LTC entitlements of Fresh Recruits. Based on the same, a set of
frequently asked questions have been answered as under:
Question 1. What are the LTC entitlements of a Fresh Recruit?
Answer: Fresh recruits to the Central Government are allowed to travel
to their home town along with their families on three occasions in a
block of four years and to any place in India on the fourth occasion.
This facility shall be available to the fresh recruits only for the
first two blocks of four years applicable after joining the Government
for the first time.
Question 2. How are the two blocks of four years applied to the Fresh Recruit?
Answer: The first two blocks of four years shall apply with reference
to the initial date of joining the Government service even though the
Govt. servant may change the job within the Government subsequently.
However, as per Rule 7 of CCS (LTC) Rules, 1988, the LTC entitlement of a
fresh recruit will be calculated calendar year wise with effect from
the date of completion of one year of regular service.
Question 3. Are the LTC blocks of four years in respect of Fresh Recruits same as the regular blocks like 2010-13, 2014-17?
Answer: No. The first two blocks of four years of fresh recruits will
be personal to them. On completion of eight year of LTC, they will be
treated at par with other regular LTC beneficiaries as per the
prescribed blocks like 2014-17, 2018-21 etc.
Question 4. If a fresh recruit does not avail LTC facility in a particular year, can he/she avail it in the next year?
Answer: No. Carryover of LTC to the next year is not allowed in case of
a fresh recruit as he is already entitled to every year LTC. Hence, if a
fresh recruit does not avail of the LTC facility in any year, his LTC
will deem to have lapsed with the end of that year.
Question 5. How will the LTC entitlements of a Fresh Recruit be exercised after the completion of eight years of service?
Answer: (a) After the completion of eight years of service, when the
next LTC cycle of fresh recruit coincides with the beginning of the
second two year block (eg. 2016-17) of the running four year block
(2014-17), he will be eligible only for ‘Home Town’ LTC if he/she has
availed ‘Any Place in India’ LTC in the eighth year. Cases, where the
new LTC cycle of fresh recruit coincides with the second year of the
running two year block (ex. 2017 of 2016-2017), he will not be eligible
for LTC in that year. Refer illustrations 1 & 3 for further
explanation. (b) At the end of the eighth year of LTC, when the new LTC
cycle of a fresh recruit coincides with the beginning of a regular four
year block, his entitlement in the regular block will be exercised as
per the usual LTC Rules. Refer illustration 2.
Question 6. How will the LTC entitlement computed in case of a fresh recruit joining the service on 31st December of any year?
Answer: A fresh recruit who joins the Government service on 31st
December of any year, will be eligible for LTC w.e.f. 31st December of
next year. Since, 31st December is the last date of a calendar year, his
first occasion of LTC ends with that year. Hence, he may avail his
first Home Town LTC on the last day of that year. From next year onwards
he would be eligible for the remaining seven LTCs. Refer illustration
3.
Question 7. How will the entitlements of a fresh recruit be computed who has joined the Govt. service before 01.09.2008?
Answer: A fresh recruit who has joined Government service before
01.09.2008 (i.e before the introduction of this scheme) and has not
completed his first eight years of service as on 01.09.2008 will be
eligible for this concession for the remaining time-period till the
completion of first eight years of his/ her service. Refer illustration
4.
Question 8. Can a fresh recruit whose Home Town and Headquarters are same, avail LTC to Home Town?
Answer: No. A fresh recruit whose Home Town and Headquarters are same,
cannot avail LTC to Home Town. He may avail LTC to any place in India on
the fourth and eighth occasion only. As per Rule 8 of CCS (LTC) Rules,
1988, LTC to Home Town shall be admissible irrespective of the distance
between the Headquarters of the Govt. servant and his Home Town which
implies that Headquarters and Home Town should be at different places.
Illustration
Illustration 1:
An
employee joins the Government service on 1st September, 2008. As per
the CCS (LTC) Rules, he will become eligible for LTC with effect from
1st September, 2009 (i.e. after the completion of one year of regular
service). His entitlement for Home Town / All India would be as under:
Year of LTC
Type of LTC
LTC Occasion
01.09.2008 – 31.08.2009
Nil
-
01.09.2009 – 31.12.2009
Home Town
1st
01.01.2010 – 31.12.2010
Home Town
2nd
01.01.2011 – 31.12.2011
Home Town
3rd
01.01.2012 – 31.12.2012
Any Place in India
4th
01.01.2013 – 31.12.2013
Home Town
5th
01.01.2014 – 31.12.2014
Home Town
6th
01.01.2015 – 31.12.2015
Home Town
7th
01.01.2016 – 31.12.2016
Any Place in India
8th
01.01.2017 – 31.12.2017
Nil
-
01.01.2018 – 31.12.2021
New LTC Block
Explanation
1.After
the completion of the first eight years, when the fresh recruit gets
into the middle of the running regular block of four calendar years (ex.
2014-2017) where the new LTC cycle of fresh recruit coincides with the
second year of the running two year block (ex. 2017 of 2016-2017), he
will not be eligible for LTC in that year (i.e. 2017).
2.It can be
seen from above that LTC entitlement for a fresh recruit is calculated
calendar year wise with effect from the date of completion of one year
of regular service.
Illustration 2:
An
employee joins the Government service on 1st January, 2009. As per the
CCS (LTC) Rules, he will become eligible for LTC with effect from 1st
January, 2010 (i.e. after the completion of one year of regular
service). His entitlement for Home Town / All India LTC would be as
under:
Year of LTC
Type of LTC
LTC Occasion
01.01.2009 – 31.12.2009
Nil
–
01.01.2010 – 31.12.2010
Home Town
1st
01.01.2011 – 31.12.2011
Home Town
2nd
01.01.2012 – 31.12.2012
Home Town
3rd
01.01.2013 – 31.12.2013
Any Place in India
4th
01.01.2014 – 31.12.2014
Home Town
5th
01.01.2015 – 31.12.2015
Home Town
6th
01.01.2016 – 31.12.2016
Home Town
7th
01.01.2017 – 31.12.2017
Any Place in India
8th
01.01.2018 – 31.12.2021
New LTC Block
Explanations:
1.A
the end of the eighth year of LTC, when the new LTC cycle of a fresh
recruit coincides with the beginning of a regular four year block, his
entitlement in the regular block will be exercised as per the usual LTC
Rules.Explanations: Illustration 3:
An
employee joins the Government service on 31st December, 2011. As per the
CCS (LTC) Rules, he will become eligible for LTC with effect from 31st
December, 2012 (i.e. after completion of one year of regular service).
His entitlement for Home Town / All India LTC would be as under:
Year of LTC
Type of LTC
LTC Occasion
31.01.2011 – 30.12.2012
Nil
–
31.12.2012
Home Town
1st
01.01.2013 – 31.12.2013
Home Town
2nd
01.01.2014 – 31.12.2014
Home Town
3rd
01.01.2015 – 31.12.2015
Any Place in India
4th
01.01.2016 – 31.12.2016
Home Town
5th
01.01.2017 – 31.12.2017
Home Town
6th
01.01.2018 – 31.12.2018
Home Town
7th
01.01.2019 – 31.12.2019
Any Place in India
8th
01.01.2020 – 31.12.2021
Home Town
–
01.01.2022 – 31.12.2025
New LTC Block
Explanations:
i.
A fresh recruit who joins on 31st December of any year, will be
eligible for LTC w.e.f. 31st December of next year. Since, 31st December
is the last date of that calendar year, his first occasion of LTC ends
with that year. Hence, he may avail his first home town LTC on that day
only (eg. 31st December, 2012). From next year onwards he will be
eligible for the remaining seven LTCs.
ii. After the completion of
eight years of service, when the next LTC cycle of fresh recruit
coincides with the beginning of the second two year block (eg. 2020-21)
of the running four year block (2018-21), he will be eligible only for
the ‘Home Town’ LTC in that block if he has availed of ‘Any Place in
India’ LTC in the eighth year. In case, the fresh recruit forgoes his
eighth year LTC, then he has a choice to avail either ‘Any Place in
India’ or ‘Home Town’ LTC in the following two year block (i.e. in
2020-21). Illustration 4:
An employee joins
the Government service on 10th May, 2006. As per the CCS (LTC) Rules,
he will become eligible for LTC with effect from 10th May, 2007 (i.e.
after the completion of one year of regular service). His entitlement
for Home Town / All India LTC would be as under:
YEAR OF LTC
TYPE OF LTC
LTC OCCASION
10.05.2006 – 09.05.2007
Nil
–
10.05.2007 – 31.12.2007
Home Town/ Any Place in India
1st
01.01.2008 – 31.12.2008
Home Town
2nd
01.01.2009 – 31.12.2009
Home Town
3rd
01.01.2010 – 31.12.2010
Any Place in India
4th
01.01.2011 – 31.12.2011
Home Town
5th
01.01.2012 – 31.12.2012
Home Town
6th
01.01.2013 – 31.12.2013
Home Town
7th
01.01.2014 – 31.12.2014
Any Place in India
8th
01.01.2015 – 31.12.2015
Nil
–
01.01.2016 – 31.12.2017
Home Town
–
Explanations:
A
fresh recruit who has joined the Government service before 01.09.2008
(i.e. before the introduction of this scheme) and has not completed his
first eight years of service as on 01.09.2008 will be eligible for this
concession for the remaining time-period till the completion of first
eight years of his/ her service.
DoPT: Procedure for booking of air-tickets on LTC- compliance of instructions regarding.
No. 31011/2/2018-Estt (A.IV)
Government of India
Ministry of Personnel, Public Grievances and Pensions
Department of Personnel and Training
Establishment A-IV Desk
North Block, New Delhi-10001
Dated: December 10, 2018
OFFICE MEMORANDUM
Subject:- Procedure for booking of air-tickets on LTC - compliance of instructions regarding.
The
undersigned is directed to refer to this Department's O.M. No.
31011/5/2014-Estt.A-IV dated 24.09.2014, 23.09.2015 and 21.08.2017 on
the procedure for booking of air tickets on LTC and to say that as per
the extant instructions, whenever a Government servant claims LTC by
air, he/she is required to book the air tickets directly from the
airlines (Booking counters, website of airlines) or by utilizing the
services of the authorized travel agents viz. 'M/s Balmer Lawrie &
Company', 'M/s Ashok Travels & Tours' and 'IRCTC' (to the extent
IRCTC is authorized as per DoPT O.M. No. 31011/6/2002-Est(A) dated
02.12.2009) while undertaking LTC journey(s).
2. In this regard,
it is observed that despite reiterating the above instructions from time
to time, this Department still continues to receive numerous references
from various Ministries/Departments and individuals seeking relaxation
for booking of air tickets for the purpose of LTC through private travel
agents. In most of the cases, the common reasons cited by the
Government employees are lack of awareness of the rules and work
exigencies.
3. Therefore, all the Ministries/Departments are
advised to ensure wide circulation and strict compliance of the
guidelines stated in para 1 of this OM. This point may also be
emphasized by the Administration whenever any advance is sought or
intention to avail LTC is conveyed by the Government servant. It is
stated that henceforth only those cases, where it is established that
bonafide mistake has occured and the Administrative Ministry/Department
is satisfied that undue hardship is being caused to the Government
servant, shall be considered by this Department for relaxation provided
that the information is received in the Proforma enclosed along with
supporting documents.
End.: As above
(Surya Na ayan Jha)
Under Secretary to the Government of India
To
The Secretaries
All Ministries/Departments of Government of India
(As per the standard list)
Sub: Admissibility of SPORTS (Society for Promotion of Nature Tourism and Sports) tour package to Lakshadweep Islands on ships operated by Lakshadweep Administration on LTC.
A Copy of Government of India, Ministry of Personnel, Public Grievances and Pensions (Department of Personnel and Training) Office Memorandum No. 31011/10/2017-Estt.A-IV dated 11.10.2018 on the above subject is forwarded herewith for your information, guidance and compliance please.
Sub: Travel entitlements of Government employees for the purpose of LTC post Seventh Central Pay Commission - clarification reg.
A Copy of Government of India, Ministry of Personnel, Public Grievances and Pensions (Department of Personnel and Training) Office Memorandum No. 31011/08/2017-Estt.A-IV dated 18.10.2018 on the above subject is forwarded herewith for your information, guidance and compliance please.
LTC-80 Scheme: Air India LTC Revised Fare List Nov 2018
Air India released an another updated list of Air Fare Nov 2018
Air India LTC Revised Fare List Nov 2018
SECTOR & V.V
HLTC (ECONOMY CLASS)
DLTC (EXECUTIVE CLASS)
Basic Fare
Basic Fare
Agartala
Kolkata
8750
17880
Agra
Delhi
8750
17880
Agra
Khajuraho
8750
17880
Agra
Varanasi
9500
19320
Ahmedabad
Chennai
17500
35400
Ahmedabad
Delhi
11050
22440
Ahmedabad
Mumbai
8750
17880
Aizawl
Imphal
8750
17880
Aizawl
Kolkata
8750
17880
Amritsar
Delhi
8750
17880
Amritsar
Mumbai
17500
35400
Amritsar
Nanded
17500
35400
Aurangabad
Delhi
15050
30560
Aurangabad
Mumbai
8250
21000
Bagdogra
Delhi
15200
30600
Bagdogra
Kolkata
8750
17880
Bengaluru
Bhubaneshwar
15100
30600
Bengaluru
Chennai
8750
17880
Bengaluru
Delhi
19900
40200
Bengaluru
Goa
9500
19320
Bengaluru
Guwahati
19900
40200
Bengaluru
Hubli
8750
17880
Bengaluru
Hyderabad
8750
17880
Bengaluru
Kolkata
17500
35400
Bengaluru
Mumbai
11050
22440
Bengaluru
Trivandrum
9500
19320
Bhopal
Delhi
9500
19320
Bhopal
Mumbai
12400
26960
Bhubaneshwar
Delhi
15100
30600
Bhubaneshwar
Hyderabad
11350
22440
Bhubaneshwar
Kolkata
8750
17880
Bhubaneshwar
Mumbai
17500
35400
Chandigarh
Delhi
8750
17880
Chandigarh
Leh
8750
17880
Chandigarh
Mumbai
17500
35400
Chandigarh
Pune
17500
35400
Chennai
Coimbatore
8750
17880
Chennai
Delhi
19900
40200
Chennai
Goa
9700
19320
Chennai
Hyderabad
9500
19320
Chennai
Kochi
9500
19320
Chennai
Kolkata
17500
35400
Chennai
Madurai
8750
17880
Chennai
Mumbai
15100
30600
Chennai
Portblair
17500
35400
Chennai
Trivandrum
9500
19320
Coimbatore
Delhi
19900
40200
Coimbatore
Mumbai
15100
30600
Delhi
Gaya
11050
22440
Delhi
Goa
17500
35400
Delhi
Guwahati
17500
35400
Delhi
Hyderabad
15100
30600
Delhi
Imphal
19900
40200
Delhi
Indore
9500
19320
Delhi
Jaipur
8750
17880
Delhi
Jammu
9500
19320
Delhi
Jodhpur
8750
17880
Delhi
Khajuraho
8750
17880
Delhi
Kochi
19900
48240
Delhi
Kolkata
17500
35400
Delhi
Leh
11100
19320
Delhi
Lucknow
8750
17880
Delhi
Mumbai
15100
30600
Delhi
Nagpur
11350
22440
Delhi
Patna
11350
22440
Delhi
Port Blair
28700
51600
Delhi
Pune
15100
30600
Delhi
Raipur
12050
22440
Delhi
Rajkot
13300
22440
Delhi
Ranchi
15100
30600
Delhi
Srinagar
9600
19320
Delhi
Surat
13300
22440
Delhi
Tirupati
19900
40200
Delhi
Trivandrum
20500
49680
Delhi
Udaipur
9500
19320
Delhi
Vadodra
11250
22440
Delhi
Varanasi
9500
19320
Delhi
Vijayawada
17500
35400
Delhi
Vishakhapatnam
17500
35400
Dibrugarh
Kolkata
11600
22440
Dimapur
Kolkata
9500
19320
Gaya
Kolkata
8750
17880
Gaya
Varanasi
8750
17880
Goa
Mumbai
8750
17880
Guwahati
Imphal
8750
17880
Guwahati
Kolkata
8750
17880
Hubli
Mumbai
8750
17880
Hyderabad
Kolkata
15150
30600
Hyderabad
Mumbai
9500
19320
Hyderabad
Tirupati
8750
17880
Hyderabad
Vijayawada
8750
17880
Hyderabad
Vishakhapatnam
9500
19320
Imphal
Kolkata
9500
19320
Indore
Mumbai
9500
19320
Jaipur
Mumbai
12050
22440
Jammu
Leh
10250
17880
Jammu
Srinagar
8750
17880
Jamnagar
Mumbai
8750
17880
Jodhpur
Mumbai
13900
26960
Khajuraho
Varanasi
8750
17880
Kochi
Mumbai
15100
30600
Kochi
Trivandrum
8750
17880
Kolkata
Mumbai
19900
40200
Kolkata
Port Blair
17500
35400
Kolkata
Silchar
8750
17880
Kolkata
Varanasi
9500
19320
Kozhikode
Mumbai
13250
22440
Leh
Srinagar
8800
17880
Lucknow
Mumbai
15100
30600
Madurai
Mumbai
15100
30600
Mangalore
Mumbai
9500
19320
Mumbai
Nagpur
9500
19320
Mumbai
Pune
8100
17880
Mumbai
Raipur
13650
22440
Mumbai
Rajkot
12850
23240
Mumbai
Trivandrum
15700
30600
Mumbai
Udaipur
9500
19320
Mumbai
Varanasi
15150
30600
Mumbai
Vishakhapatnam
15100
30600
Port Blair
Vishakhapatnam
15150
30600
Raipur
Nagpur
8750
17880
Raipur
Vishakhapatnam
8750
17880
Bengaluru
Belgaum
8750
17880
Kolkata
Jaipur
17500
Bengaluru
Ahmedabad
15150
30600
Hyderabad
Guwahati
19900
40200
Bhubaneshwar
Guwahati
11350
22440
Terms & Conditions:
LTC Tickets: Change/Refund Fee will be as applicable for highest Business or Economy Class fare
Armed Forces and related discounts
: Change/ Refund Fee applicable as per RBD fare rules. All categories
of (Armed Forces, Paramilitary Forces, General Reserve Engineering
Forces, War Disabled Officers, War Widows and Gallantry Award Tickets
under RBD K to L) , (Armed Forces Bravery Award Tickets under RBD K to
L).
Applicable Fares as on 2nd November 2018
These fares are subject to Change without prior notice.**
FAQ on Allowance, Leave, MACP, LTC, Seniority and Reservation
FAQ
on Allowance, Leave, ACP, MACP, LTC, Seniority, Sexual Harassment,
Administrative Tribunals, Compassionate Appointment, Non Functional
Upgradation, Joint Consultative and Arbitration and Reservation